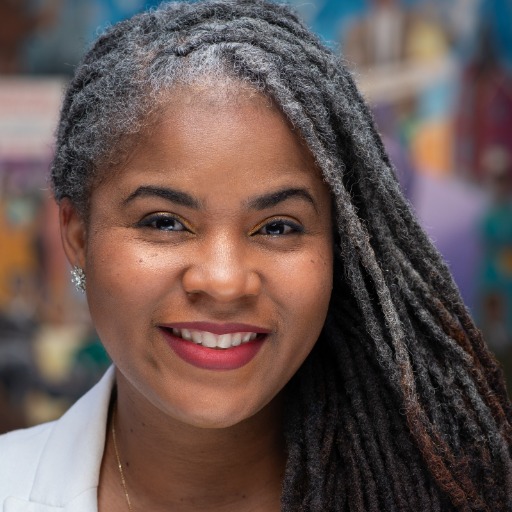
Buying a Home Is More Than a Mortgage PaymentIf you're thinking about buying a home, you've probably started with the same question most buyers ask:“How much house can I afford?”But as
Dated: September 11 2026
Views: 0
If you're thinking about buying a home, you've probably started with the same question most buyers ask:
“How much house can I afford?”
But as your Finance Bestie, I want you to ask a slightly different question:
“What home payment can I comfortably live with?”
Those two numbers aren't always the same.
As a Real Estate Broker and Accredited Financial Counselor, I believe buying a home should be about more than getting approved for a mortgage. A lender's approval tells you what you may be able to borrow. Your personal budget tells you what you can realistically afford while still saving, handling unexpected expenses, enjoying your life, and working toward your other financial goals.
That's where I come in.
I'm not just here to help you find a house. I'm here to help you understand the financial picture behind the house.
When buyers calculate affordability, they often focus on principal and interest. But your actual monthly housing cost can include:
Principal and interest
Property taxes
Homeowners insurance
Mortgage insurance, if applicable
HOA dues
Utilities
Home maintenance and repairs
A home that looks affordable based on the mortgage payment alone may feel very different once all of those expenses are included.
That's why your Finance Bestie wants you looking at the total cost of owning the home, not just the loan payment.
Affording a home isn't only about the monthly payment.
You may also need money for:
Down payment: Depending on the loan program, your down payment could range from little to none to a larger percentage of the purchase price.
Closing costs: These can include lender fees, title-related expenses, prepaid taxes and insurance, and other costs associated with purchasing the home.
Inspections and due diligence: Depending on the property and your contract, you may have expenses before closing that need to be paid out of pocket.
Moving expenses: Moving, furniture, appliances, deposits, and other costs can add up quickly.
Emergency reserves: This one is easy to overlook. You don't want to use every dollar you have to get the keys and then have nothing left when the water heater decides to quit.
As your Finance Bestie, I'm going to encourage you to think about what happens after you get the keys, not just how you're going to get them.
Buyers understandably pay close attention to interest rates. A lower rate can make a significant difference in the monthly payment.
But don't evaluate a home based on the interest rate alone.
Consider the entire package:
Purchase price + interest rate + loan terms + seller concessions + property taxes + insurance + HOA + your overall financial situation.
A seller offering money toward closing costs may change how much cash you need to bring to closing.
A builder may offer an attractive interest rate or incentives through its preferred lender.
Another seller may have a lower purchase price but offer fewer concessions.
The “best deal” isn't always the home with the lowest price or the lowest advertised rate.
It's the combination that makes the most sense for you.
And that's exactly the kind of conversation I want to have with my clients.
This is where the financial conversation becomes especially important.
Before buying, ask yourself:
Will I still be able to save every month?
Will I have money available for unexpected repairs?
Can I comfortably afford my other debts?
Will I still be able to enjoy the things that matter to me?
What happens if my income temporarily decreases?
Am I still contributing toward retirement?
Does this purchase support my long-term financial goals?
A home can be one of the most significant assets you ever purchase.
But that doesn't mean you should stretch yourself as far as possible just because a lender says you qualify.
This is one of the biggest distinctions I want buyers to understand.
Preapproval answers:
“How much might a lender be willing to lend me?”
Your personal budget answers:
“How much can I comfortably spend on housing while still living the life I want?”
Those numbers may be different.
And that's okay.
In fact, I think it's healthy when buyers understand the difference.
My answer is:
Buy the home that fits your life—not just the home you qualify for.
Your future self will probably thank you for leaving some breathing room in your budget.
And if you're not sure what that number looks like yet, that's okay, too.
That's why I'm here.
As Your Finance Bestie, my goal is to help you understand both sides of the equation: the home and the money behind the home.
Because buying a house isn't just a real estate decision.
It's a financial decision, too.
And you don't have to figure it all out alone.
Whether you're ready to buy now, planning for next year, or simply wondering whether homeownership makes sense for you, let's talk.
No pressure. No judgment. Just a conversation about your goals, your numbers, and your options.
I'm Jaimie Surles—your Finance Bestie, who also sells homes.
Real Estate Broker | Accredited Financial Counselor
Long & Foster Real Estate
Buying a Home Is More Than a Mortgage PaymentIf you're thinking about buying a home, you've probably started with the same question most buyers ask:“How much house can I afford?”But as
 Copyright 2026 Triangle MLS, Inc. of North Carolina. All rights reserved.
The data relating to real estate for sale on this web site comes in part from the Triangle MLS, Inc. of North Carolina. Real estate listings held by brokerage firms other than Long & Foster Raleigh, NC - Realty are marked with the Broker Reciprocity logo and detailed information about them includes the name of the listing brokers. Brokers make an effort to deliver accurate information, but buyers should independently verify any information on which they will rely in a transaction. The listing broker shall not be responsible for any typographical errors, misinformation, or misprints, and they shall be held totally harmless from any damages arising from reliance upon this data. This data is provided exclusively for consumer's personal, noncommercial use.
Closed (sold) listings may have been listed and/or sold by a real estate firm other than the firm(s) featured on this website. Closed data is not available until the sale of the property is recorded in the MLS. Home sale data is not an appraisal, CMA, competitive or comparative market analysis, or home valuation of any property.
Listings marked with an icon are provided courtesy of the Triangle MLS, Inc. of North Carolina, Internet Data Exchange Database.
This site is monitored for scraping. Any use of listing data obtained from this web site, other than by a consumer looking to purchase real estate, is prohibited.
This data has been updated as of September 22, 2026 4:35 AM UTC
